The one deadline that matters: losing job-based coverage opens a 60-day window to enroll in a new plan, no matter the time of year. Miss it, and you may be waiting for open enrollment.
- $9,325average yearly premium for single employer coverage in 2025, the bill COBRA hands to you
- 102%the most a COBRA plan can charge, the full premium plus a 2 percent admin fee
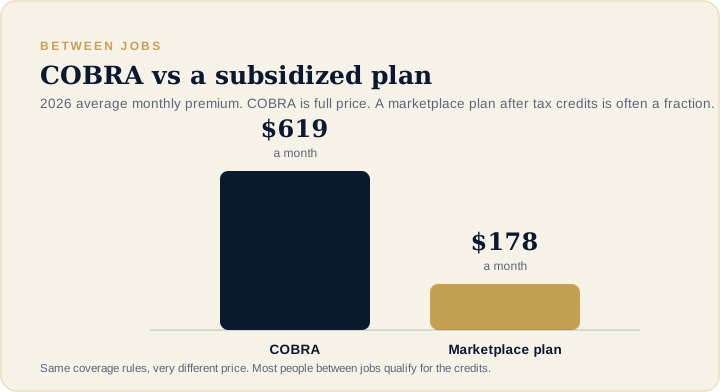
- $178average monthly marketplace premium after tax credits for 2026
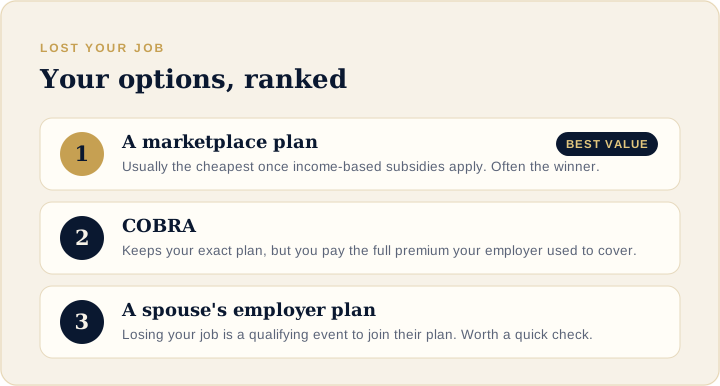
Option 1: A marketplace plan, usually the winner
Losing employer coverage is a qualifying life event, which unlocks a Special Enrollment Period on the Affordable Care Act (ACA) marketplace. Here's the part most people miss: marketplace subsidies are based on your expected income for the year, and CMS reports that 87 percent of people who picked a marketplace plan for 2026 chose one with a premium tax credit. If your income just dropped because you're between jobs, you may qualify for far more help than you'd expect. The average marketplace premium for 2026 was $619 a month before tax credits and $178 a month after them. Many people in this situation end up paying a fraction of what COBRA costs, sometimes very little at all, for a real major medical plan.
You also do not have to wait for your last day. HealthCare.gov lets you qualify if you expect to lose coverage in the next 60 days, so you can have the new plan lined up before the old one ends. You can estimate your subsidy with my calculator in a couple of minutes. If you have already lined up a new job, keep in mind the employer plan can carry a waiting period of up to 90 days before it starts, so a marketplace plan can bridge that gap too. Subsidy rules are also shifting for 2027, which I break down in my guide to the 2027 subsidy cliff.
Option 2: COBRA, same plan, full price
COBRA lets you keep the exact plan you had, which sounds comforting. The catch: your employer was quietly paying most of the premium, and now you pay all of it, plus an admin fee. KFF's 2025 Employer Health Benefits Survey puts the average total premium at $9,325 a year for single coverage and $26,993 a year for family coverage. The average worker was only paying $1,440 and $6,850 of that. Under federal rules a COBRA plan can charge up to 102 percent of the full cost, which works out to roughly $793 a month for single coverage and $2,294 a month for a family at those averages.
The basic COBRA rules, from the Department of Labor:
- It applies to employers with 20 or more employees. Some states have their own continuation rules for smaller employers.
- You get at least 60 days to elect it, counted from the later of your election notice or the date your coverage would end.
- You get at least 45 days after electing to make the first payment.
- It usually lasts 18 months after a job loss or a cut in hours.
When COBRA genuinely makes sense: you're mid-treatment with doctors you can't switch, or you've already hit your deductible and out-of-pocket max for the year. In those cases, keeping the same plan can be worth the price. One useful quirk: you get 60 days to elect COBRA and it's retroactive to the day you lost coverage, so it can act as a safety net while you decide.
The COBRA trap nobody mentions
This one catches people every year. If you elect COBRA and later decide it costs too much, dropping it does not let you switch to a marketplace plan. HealthCare.gov is clear that voluntarily dropping COBRA, or just stopping your payments, does not qualify you for a Special Enrollment Period. You would be waiting for open enrollment. So make the COBRA versus marketplace decision inside your first 60 days, with real numbers in front of you.
Option 3: A spouse's employer plan
Your job loss is also a qualifying event for your spouse's plan. Their employer typically allows about 30 days to add you. If that plan is well subsidized, it's often the cheapest path of all, so check it before anything else.
What about short-term plans?
In many states, short-term medical plans can bridge a brief gap for less money. They're real coverage for accidents and new illness, but they're not ACA plans: pre-existing conditions generally aren't covered, and benefits are capped. For a known, short gap they can be a smart tool. As your ongoing coverage, they're usually the wrong fit. This is exactly the kind of trade-off worth a ten-minute conversation.
Losing your job late in the year
If your coverage ends in the fall, open enrollment may line up with your special enrollment window. On HealthCare.gov, the dates for 2027 coverage are below. States that run their own exchanges can set different deadlines.
- November 1, 2026Open enrollment begins for 2027 coverage
- December 15, 2026Last day to choose a plan that starts January 1, 2027
- January 15, 2027Open enrollment closes on HealthCare.gov
If you are going out on your own instead of looking for another job, read my guide to self employed health insurance, because estimating freelance income for a subsidy has its own traps. And if your job ended a while ago and you are not sure your window is still open, here is how special enrollment works.
Bottom line
Check a spouse's plan first if you have one. Then compare a subsidized marketplace plan against COBRA, with your new income. The marketplace usually wins by a wide margin. And move inside the 60-day window. I'm Carson Hornish, an independent broker licensed in every state (NPN 21581721). This comparison is exactly what I do, and it costs you nothing. Here is why a broker is free.
Common questions
How long do I have to get health insurance after losing my job?
Losing job-based coverage is a qualifying life event that opens a 60-day Special Enrollment Period on the ACA marketplace, and you can apply up to 60 days before your coverage ends. You also have at least 60 days to elect COBRA, which applies retroactively to the day your coverage ended.
Is COBRA or a marketplace plan cheaper after a job loss?
Usually the marketplace. COBRA charges up to 102 percent of the full premium your employer used to subsidize, while marketplace subsidies are based on your expected income, which is typically lower between jobs. For 2026 the average marketplace premium was $178 a month after tax credits, according to CMS.
How much does COBRA cost?
COBRA can cost up to 102 percent of the full plan premium. KFF's 2025 Employer Health Benefits Survey puts the average total premium at $9,325 a year for single coverage and $26,993 for family coverage. At 102 percent, that is roughly $793 a month for single coverage and $2,294 a month for a family.
Can I switch from COBRA to a marketplace plan later?
Not just by dropping COBRA. HealthCare.gov states that voluntarily dropping COBRA or stopping your payments does not qualify you for a Special Enrollment Period. You can switch during open enrollment, when your COBRA runs out, or if you have another qualifying life event.
Does losing my job qualify me for a Special Enrollment Period?
Yes. Losing employer health coverage is a qualifying life event, so you can enroll in a marketplace plan outside open enrollment. You can qualify if you lost coverage in the past 60 days or expect to lose it in the next 60 days.
What are the alternatives to COBRA?
The main alternatives to COBRA are an ACA Marketplace plan, a spouse's employer plan, or a short term plan. Losing job-based coverage opens a 60 day special enrollment window, and a Marketplace plan priced on your new income is usually far cheaper than COBRA for the same or better coverage. A broker can compare your COBRA quote against every alternative to COBRA at no cost.
How does COBRA insurance work in Florida?
Federal COBRA works the same in Florida as anywhere else and applies to employers with 20 or more employees. Florida also has a state continuation option, sometimes called mini-COBRA, for smaller employers. Either way, COBRA in Florida means keeping your old plan at full price, so most people between jobs compare Florida COBRA insurance against a Marketplace plan priced on their new income first.
Between jobs right now?
Tell me your ZIP and household, and I'll compare COBRA against every subsidized plan you qualify for, free, no pressure, usually same-day.
Get my free comparison →Sources
- KFF, 2025 Employer Health Benefits Survey
- U.S. Department of Labor, An Employee's Guide to Health Benefits Under COBRA
- HealthCare.gov, Special Enrollment Period
- CMS, Exchange coverage remains near record high as 23.1 million enroll for 2026
- CMS, Health Insurance Exchanges 2026 Open Enrollment Report
- CMS enrollment deadlines for 2027 coverage, via healthinsurance.org